MAS Insurance Regulatory Developments: What Singapore Insurers Need to Act On
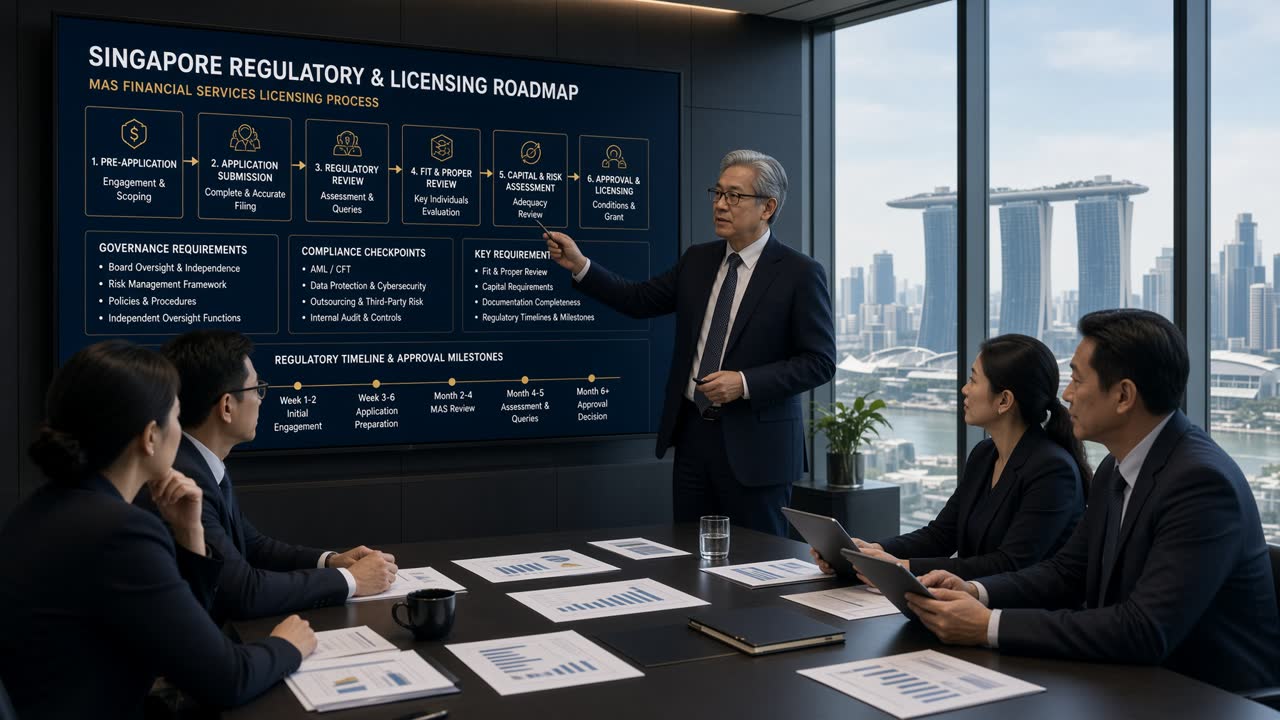
The Monetary Authority of Singapore has intensified its supervisory focus on insurance company governance, risk culture and senior management accountability. Recent thematic reviews have highlighted gaps in board oversight of risk appetite, weaknesses in outsourcing due diligence and inconsistencies in policyholder disclosure. We examine the key findings, the regulatory expectations boards are being held to, and how insurers can close the most common gaps before the next supervisory cycle.
What the Regulatory Environment Looks Like Now
Singapore's insurance sector operates under one of the most demanding supervisory frameworks in Asia Pacific. The Monetary Authority of Singapore has made clear through its inspection findings, thematic reviews and published expectations that governance quality, risk management discipline and policyholder conduct standards are not aspirational targets but enforceable minimum standards.
For insurers operating in Singapore, whether locally incorporated, branches of foreign insurers or captives, the practical implication is the same: supervisory engagement has deepened, the areas under scrutiny have broadened, and the consequences of gaps have become more visible.
This briefing sets out where MAS has been focusing its attention, what the specific expectations look like in practice, and the steps insurers should take to close common gaps before the next supervisory cycle.
Governance and Board Accountability
MAS has made board and senior management accountability a consistent theme in its engagement with insurers. The Financial Institutions Governance Regulations establish minimum requirements, but the supervisory expectation goes beyond structural compliance. This sits at the heart of enterprise risk management as regulators expect it to be practised.
Boards are expected to provide substantive oversight of risk appetite, not simply approve a document. Thematic reviews have found gaps in how risk appetite statements translate into business decisions, and in how boards receive and challenge management information. The MAS expects boards to demonstrate that they understand the insurer's risk profile, that they have set boundaries management operates within, and that exceptions are escalated and addressed.
The specific areas that attract supervisory scrutiny include:
- Whether the board risk committee receives timely, relevant and well-prepared risk reporting
- How senior management accountability is assigned for specific risk categories and regulatory obligations
- Whether the insurer has a clear governance framework for new product approval, including conduct risk sign-off
- How the board is briefed when regulatory developments affect the insurer's operating model
Senior management accountability under Singapore's Individual Accountability and Conduct regime requires that each material obligation has a named senior individual responsible for it. Insurers should review their accountability maps against current business activities and ensure they reflect reality, not an outdated structure.
Outsourcing Due Diligence and Vendor Risk
Outsourcing remains a persistent gap area. MAS guidelines on outsourcing apply to material arrangements, which for most insurers include IT infrastructure, policy administration systems, claims handling, actuarial functions and investment management.
The common weaknesses identified in supervisory engagement include:
- Concentration risk not adequately assessed at the portfolio level across all outsourced functions
- Initial due diligence conducted but not refreshed when vendor circumstances change materially
- Contracts that do not give the insurer adequate audit rights or business continuity assurances
- No clear escalation process when a vendor reports an incident or breach
- Oversight of sub-contractors not covered in the due diligence framework
The practical test MAS applies is whether the insurer could demonstrate, if asked, that it understands what is happening inside its material vendors. That requires more than annual questionnaires. It requires proportionate ongoing monitoring, periodic on-site or document-based reviews for critical vendors, and a clear record of how issues identified are tracked to closure.
Insurers that use cloud service providers for core functions should also ensure their arrangements meet MAS cloud guidelines, including the requirements around data residency, access rights and exit provisions.
Policyholder Conduct and Disclosure Standards
MAS has broadened its conduct supervisory focus to include the full customer journey, from pre-sale disclosure through to claims handling and complaints management. This applies to both direct distribution and intermediated models.
For pre-sale disclosure, the expectation is that customers receive clear, accurate and comparable information that enables informed decisions. Where products are complex, the disclosure burden increases. MAS has been examining whether insurers can demonstrate that their disclosure materials genuinely help customers understand what they are buying, and whether the suitability frameworks applied by advisers meet the standard required.
Key areas where insurers should review their position:
- Whether product disclosure documents reflect the product as it is sold today, including any subsequent modifications
- How persistency data is monitored and whether high lapse rates trigger a conduct review
- Claims handling turnaround times and how complaints are recorded, categorised and escalated
- Whether front-line staff and advisers are trained on their disclosure obligations in a format MAS could inspect
For intermediated distribution, insurers are not absolved of conduct accountability by the intermediary relationship. MAS expects insurers to set conduct standards for their distribution partners, monitor adherence and take action where standards are not met.
AML/CFT Obligations for Insurers
MAS Notice 314 sets out the AML/CFT obligations for insurers, and MAS expects compliance to be embedded in operations rather than treated as a policy exercise.
For life insurers, the higher-risk areas include single-premium products, premium-financing arrangements and high-value policies taken out by customers with limited insurance need relative to their stated financial profile. Customer due diligence must be proportionate to risk, meaning that standard CDD processes are not sufficient for higher-risk relationships.
Beneficial ownership verification has become a particular focus. Insurers should be able to demonstrate that they identify who ultimately benefits from a policy, not just the named policyholder, and that this is refreshed when the policy is reassigned or when circumstances change.
Suspicious transaction monitoring for insurers differs from banking but is not optional. Early surrender patterns, premium overpayment and subsequent refund requests, and unusual assignment patterns are among the indicators that should be captured in the insurer's alert framework.
How to Prepare for the Next Supervisory Cycle
MAS supervisory cycles for insurers vary by size and risk profile, but the preparation approach is consistent: insurers that are continuously ready for examination will perform better than those that prepare reactively.
A practical preparation checklist:
-
Governance gap assessment. Map current board and committee structures against MAS expectations. Review committee terms of reference to confirm risk oversight responsibilities are clearly assigned and being exercised.
-
Outsourcing register review. Confirm that all material outsourcing arrangements are documented, due diligence records are current, and contracts contain required provisions. Identify any arrangements where oversight has lapsed.
-
Conduct self-assessment. Review the full customer journey for your key products. Identify where disclosure could be clearer, where complaints data suggests systemic issues, and whether claims handling meets expected turnaround standards.
-
AML/CFT programme review. Confirm that your risk assessment, policies and procedures reflect current products and distribution channels. Review whether staff training is current and whether suspicious transaction monitoring is calibrated to the business you actually write.
-
Senior management accountability mapping. Confirm that accountability maps are current, that named individuals are genuinely responsible for what they are accountable for, and that there are no material gaps in coverage.
-
Documentation and record keeping. Supervisory inspections rely heavily on documentation. Confirm that board and committee minutes record substantive discussion and decision-making, not just attendees and approvals.
Working With Your Regulator
MAS supervisory engagement is generally constructive. Insurers that approach regulatory interaction transparently, respond promptly to information requests and demonstrate genuine commitment to addressing gaps typically find the supervisory relationship manageable.
Where gaps are identified, the MAS expectation is a credible remediation plan with realistic timelines, senior management ownership and genuine follow-through. Insurers that commit to remediation in principle but do not deliver in practice will find supervisory pressure intensifies.
The most effective approach is proactive. Insurers that conduct regular self-assessments, address gaps before they become supervisory findings and maintain open communication with their MAS relationship manager are better positioned than those who wait for inspection to identify issues.
If your organisation would like to work through any of the areas covered in this briefing, our regulatory compliance team is available to discuss your specific position. We assist insurers with governance reviews, outsourcing programme assessments, conduct self-assessments and AML/CFT programme reviews.
Questions about how this applies to your organisation? Our consultants are available to discuss your specific position.
More in Regulatory Compliance
Briefing details
- Category
- Regulatory Compliance
- Reading time
- 6 min read
- Published
- 30 September 2026